
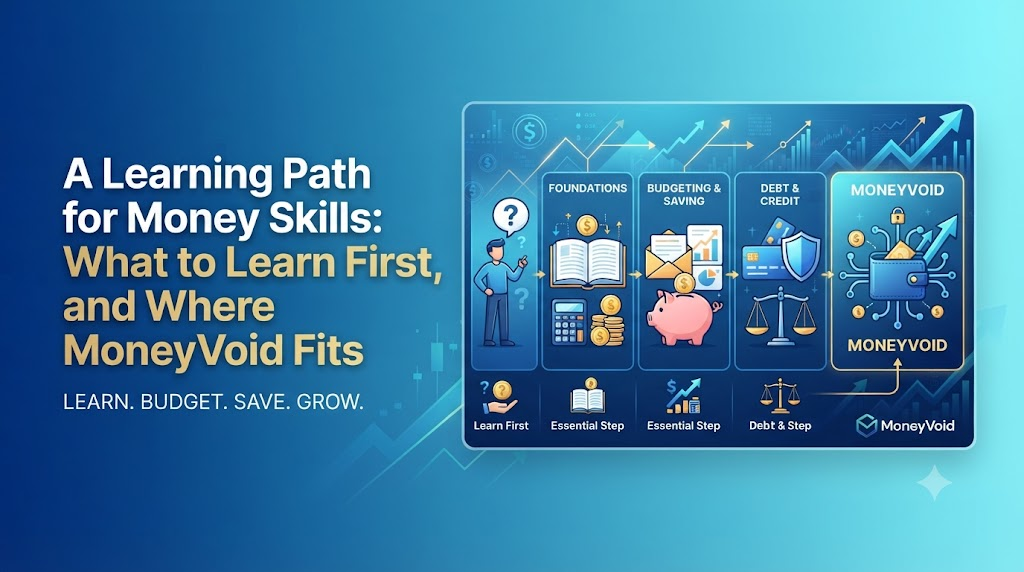
Most of us learn to read, write, and do sums at school. Very few of us learn how to read our own money. We pick it up slowly, often after a mistake: a forgotten renewal, a month that ran short, or a message that nearly fooled us.
This article treats money like any other skill. It lays out a learning path, one lesson at a time, from keeping a simple spending record to understanding how a startup counts its cash. Along the way, it shows where MoneyVoid fits. MoneyVoid is a privacy-focused personal and business finance platform that is being developed to help people understand where their money goes.
About MoneyVoid, in a Few Lines
MoneyVoid is designed for individuals, families, founders, and finance teams. It aims to help them spot unnecessary spending, keep repeating costs under control, lower financial risk, and understand where their money goes.
The platform and some of its features are still being developed, so not everything below is available today. These are the planned parts:
- Money Leak Analyzer: designed to sort expenses into categories, highlight unusually high spending, flag possible lifestyle-related leaks, and prepare monthly summaries.
- Subscription & Recurring Tracker: designed to follow repeating charges, send renewal reminders, and show unused services and possible savings.
- Startup Burn Optimizer: designed to help founders, CFOs, and operations teams model payroll, cloud, software, and marketing costs, burn rate, and remaining runway, and to test different cost-cutting ideas.
- Scam & Fraud Shield: designed to cover UPI fraud, phishing, OTP scams, fake customer-support calls, crypto scams, and what to consider after suspected fraud.
- Money Void Score: a planned score that looks at spending, debt, savings, emergency funds, and financial risks.
Early versions are planned to work through manual entry and CSV imports, so users would not need to share their banking passwords. Privacy matters because a money record is personal. It shows what you buy, where you go, and how you live.
Why It Pays to Learn This Early
Money habits are easier to build before problems appear. A person who tracks spending from the first job has a clearer view of every later choice. A founder who understands cash from the first month has more time to react when numbers change.
Learning these skills helps in practical ways:
- You can explain where your money went, with facts.
- You can spot repeating costs before they pile up.
- You can plan a budget that matches real life.
- A business can decide what to keep, change, or stop.
- You can recognize a scam before it costs you.
No special background is needed. Each lesson below builds on the one before it.
The Learning Path, Lesson by Lesson
Lesson 1: Keep a Simple Spending Record
Start with the basics. A good expense tracker India households use helps you write down each payment and put it into a category, such as rent, food, travel, school, health, or fun. Begin with a few broad categories and add more only when you need them.
Two habits matter more than any feature. The first is accuracy. Include cash, and use the same category for the same kind of spending. The second is review. Choose a regular time to read what you wrote. A tracker you never open cannot teach you anything, and a tracker full of mistakes can teach you the wrong thing.
Lesson 2: Find What Repeats
Next, look for costs that come back by themselves, such as streaming plans, gym fees, storage plans, insurance, and work software. You agree once, and the money leaves again and again.
A useful subscription tracker India users can rely on would show each plan, its price, how often it is billed, and its next renewal date. Many people also keep a simple recurring payment tracker, such as a sheet with a reminder a week before each renewal. When you review the list, ask:
- Which plans renew soon?
- Which are billed yearly and easy to forget?
- Has any price gone up?
- Do I still use each plan?
- Do I pay twice for the same thing?
- How much notice is needed to cancel?
No tool can promise to find or cancel every payment for you, so it is still wise to read your bank statements now and then.
Lesson 3: Pick a Tool and a Budget
Tracking looks back. Budgeting looks ahead. A budget is a plan for how much you intend to spend in each category.
When you compare a personal finance app India offers, check:
- Can you change the categories?
- Are the monthly summaries easy to read?
- How does data get in: by hand, by file, or by linking accounts?
- What does the privacy policy say?
- Can you export your data if you leave?
- Is it simple enough that you will use it every week?
A good budget planner app India users choose should let you set a limit for each category and see how much is left as the month goes by. Tools differ, so choose the one that fits your habits. Start with a budget you can really follow. A plan that is too strict is often dropped within weeks.
Lesson 4: Learn How Startups Count Cash Going Out
Now we move to the business side. Burn rate is how fast a startup spends its cash. Gross burn is all the money going out. Net burn is the money going out minus the money coming in.
A startup burn rate calculator takes costs such as salaries, cloud hosting, software plans, and marketing, subtracts monthly income, and shows how much cash is lost each month.
One point trips up many beginners: billed sales are not cash until the customer pays. If payments arrive late, the real burn is higher than the sales sheet suggests. Always check the bank balance, not only the invoice list.
Lesson 5: Learn How Long Cash Lasts
Once you know the burn, you can ask how long the cash will last. This is the runway. It is the estimated time a startup can operate before cash runs out. The formula is:
Runway in months = cash in the bank ÷ monthly net burn
A quick made-up example: a startup with ₹10 lakh in the bank and a net burn of ₹2 lakh has about 5 months of runway (₹10 lakh ÷ ₹2 lakh).
A startup runway calculator applies this formula, but the answer is only as good as the inputs. Before you trust it, check:
- Is the cash figure up to date?
- Will sales grow, stay flat, or fall?
- Is hiring planned?
- Will cloud and software bills rise as usage grows?
- Which costs could be reduced, and what might that change?
A runway number is an estimate, not a promise. It moves whenever income or costs move, so recalculate it every month.
Lesson 6: Look at Software Costs as a Team
Software costs grow quietly. Someone starts a trial, another team buys a tool that overlaps with it, and a person leaves while their seat stays active. Each bill looks small, but together they can become a big line in the budget.
SaaS spend management means knowing which software the company pays for, who uses it, when it renews, and whether it is still needed. A simple review would cover:
- Active licenses and idle ones.
- Tools that do the same job.
- Renewal dates and the notice needed to cancel.
- What each department spends.
- Whether the tool still fits the work.
This review helps a team find costs worth a closer look. It does not promise any fixed saving, and sometimes it shows that a tool is worth every rupee.
Lesson 7: Practice Safe Payments
Every money course needs a safety lesson. UPI is fast, and scammers rely on speed and worry. Good UPI fraud prevention starts with knowing the common tricks:
- A call from "customer care" that you did not ask for. Real support will not ask for your PIN.
- A request for an OTP. An OTP is for you alone. Never read it out.
- A "request" that takes money out. If you must enter your PIN, you are paying, not receiving.
- A message with a link that copies a bank or app. Open the official app yourself instead.
- Pressure to act right now. Slow down and verify.
Remember that entering your UPI PIN generally approves a payment. Receiving money does not normally need a PIN. If you think you have been tricked, contact your bank or payment provider promptly and follow their official reporting guidance. No tool, including any planned in MoneyVoid, can stop all fraud, so a pause before you act is your best protection.
Lesson 8: Read a Score Carefully
A financial health score is one number meant to sum up several parts of your finances. MoneyVoid's planned Money Void Score is intended to look at spending, debt, savings, emergency funds, and financial risks. An emergency fund is money set aside for surprises, such as a medical bill or a gap between jobs. The score's formula, scale, and launch details have not been shared, so it is best not to guess them.
The key lesson is that a score is a guide, not a grade. It cannot see your whole life, and it cannot predict what will happen next. Two people with the same number may be in very different places.
Lesson 9: Know Where Your Data Goes
Before you hand any tool your money data, learn how the data gets in. There are three common ways: typing it in, uploading a file, or linking accounts directly. The table later in this article compares them.
Whichever you choose, find out what data is collected, where it is stored, who can see it, how long it is kept, whether it is shared, and how you can delete it. No service can honestly say that privacy risk is gone. MoneyVoid's early plan for manual entry and CSV imports is one way to share less, but read the final privacy details once they are published.
Lesson 10: Connect Home and Work Money
The last lesson ties everything together. A household and a company have different costs, but the habit is the same: understand what you spend before you decide what to change. A household thinks about rent, school fees, and food. A company thinks about salaries, servers, and sales. The risks differ too, so a cut that is wise for one can be a mistake for the other. Treat any method as a starting point, not a rule for everyone.
A Five-Step Study Plan for Week One
- Pick one tool. Choose a sheet, a notebook, or an app, and stick with it for a month.
- Add one month of records. Enter or import your spending and put each item in a category.
- Tag what repeats. List every plan that renews, with its price and date.
- Write a small plan. Set limits for each category, or cost figures a business can defend.
- Review and note what you learned. Compare with next month and adjust.
Beginner Mistakes to Skip
- Starting with too many categories. Keep them broad at first.
- Leaving out cash. Totals will come out too low.
- Missing yearly renewals. They come once and are easy to forget.
- Setting a budget that is too strict. It rarely lasts a month.
- Counting billed sales as cash. Unpaid invoices cannot pay salaries.
- Treating runway as a fixed date. It moves with income and costs.
- Keeping software seats nobody uses. Small bills add up.
- Uploading money data without reading privacy terms. Check first.
- Approving a UPI request because it sounds urgent. Stop and verify.
- Reading a score as the whole story. It is only one view.
A Made-Up Freelancer's Cushion
A freelance developer has irregular income. Her essential costs are ₹45,000 a month, and she has ₹1,35,000 set aside as an emergency fund.
The fund covers ₹1,35,000 ÷ ₹45,000 = 3 months of essential costs if all income stopped.
Now picture a slow month where she earns only ₹30,000. She is short by ₹45,000 − ₹30,000 = ₹15,000. If she fills the gap from the fund each slow month, it would last ₹1,35,000 ÷ ₹15,000 = 9 such months.
The numbers show why people with irregular income look at their cushion in two ways: as months of costs, and as months of shortfalls. The right size of a cushion depends on the person, so this is only a way to think about it.
Three Ways to Get Data In, Compared
| Method | How it works | Effort | What you share | A point to check |
|---|---|---|---|---|
| Manual entry | You type each payment yourself | Highest | Only what you type | Do you have the time to keep up? |
| CSV import | You upload a statement file | Medium | The contents of the file | Remove details you do not need before uploading |
| Direct account link | The tool connects to your accounts | Lowest | Access to account data | Read the privacy terms closely and know how to disconnect |
Questions Learners Often Ask
Where should a beginner start with money tracking?
Start with one month of records and a few broad categories. A simple sheet is enough to begin.
What is a CSV file, and how is it used?
A CSV file is a plain table saved as text, with values separated by commas. Many banks let you download statements in this form, and some tools can read it.
What is the difference between fixed and variable costs?
Fixed costs stay about the same each month, such as rent. Variable costs change, such as food or travel.
What does "net" mean in net burn?
It means after subtracting income. Net burn is the money going out minus the money coming in.
Why should a company track software costs by team?
It shows who uses which tools and where costs are growing, which makes it easier to ask whether each tool is still needed.
Why do scammers ask for an OTP?
An OTP can approve a login or a payment. If you share it, you may give the scammer the permission they need. Never share it.
How often should I export or back up my money records?
Once a month is a reasonable habit. It keeps a copy under your control if you ever change tools.
Wrapping Up the Path
Money skills are built one lesson at a time. Keep a simple record, find what repeats, choose a budget you can follow, and for a business, understand burn and runway. Learn the common UPI traps, read any score with care, and know where your data goes.
MoneyVoid is being developed to bring these ideas together for families, founders, and finance teams, with privacy in mind. Not every planned feature is available yet, so judge any tool by what it truly offers when you use it.


Top comments (0)